A New Era in Credit Card Limits: What Awaits Millions in 2026?
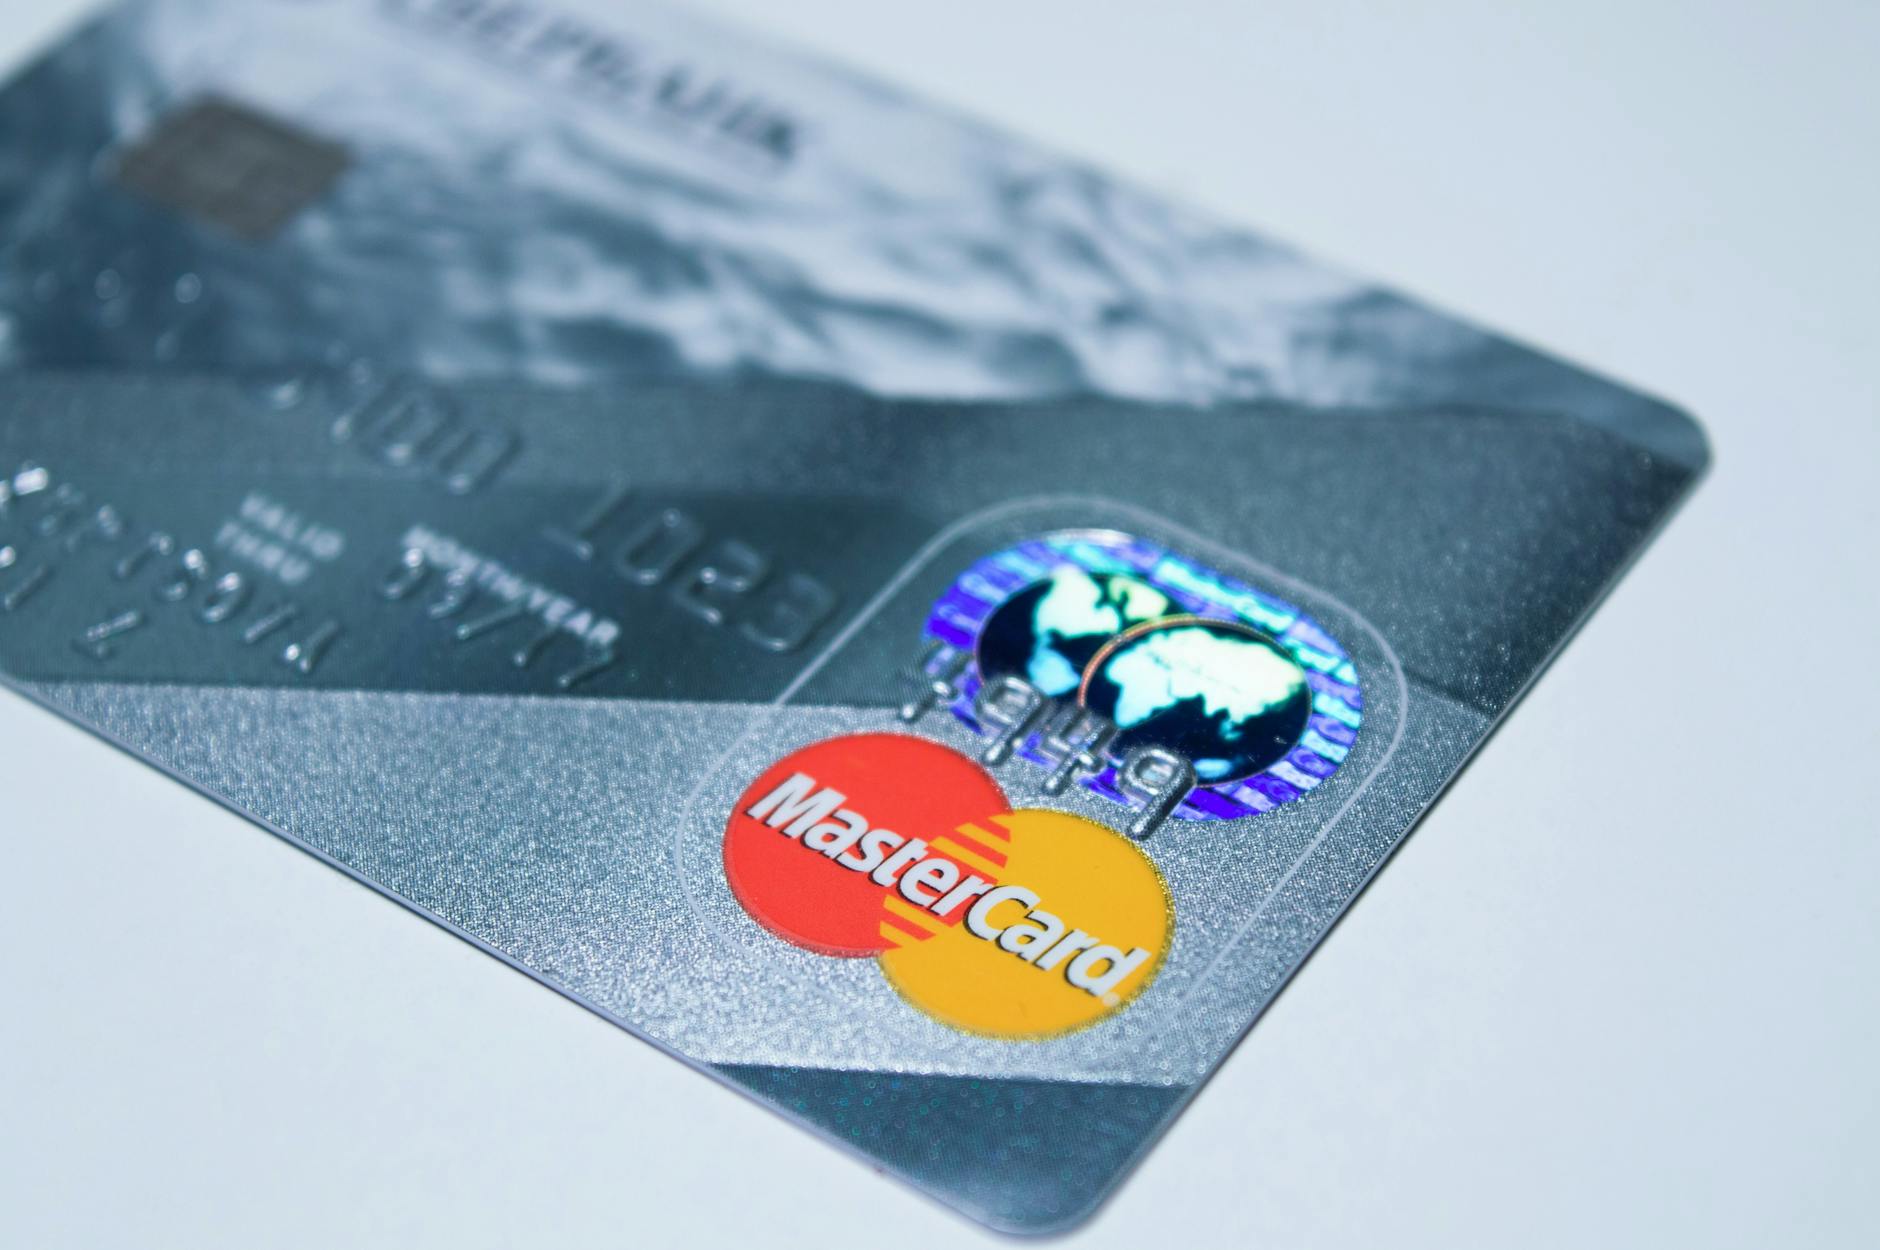
As we enter the final quarter of 2026, a fundamental regulatory process that closely concerns millions of credit card users in Turkey has gained momentum. The new regulations implemented by the Banking Regulation and Supervision Agency (BRSA) are fundamentally changing market dynamics, particularly regarding the determination of credit card limits and the updating of minimum payment rates. The scrutiny of limits above 400,000 TL indicates that individual borrowing capacity will be tied more strictly to income levels.
This process represents a broad financial discipline package that covers not only card limits but also phone loans and installment spending habits. Data reflected in news agencies since September reveals that the BRSA is taking a proactive stance to keep household debt ratios under control and maintain financial stability. These regulations, which millions of cardholders have been waiting for, are essentially considered part of the tightening measures in the economy.
Credit card usage is the most important determinant of consumption habits in Turkey. However, recent inflationary pressures and rising household debt ratios have forced regulatory agencies to take action. The audit of whether high-limit cards are consistent with income declarations has initiated a new 'income-focused limit determination' era in the banking sector. This indicates that cardholders will now undergo a much more detailed financial screening for limit increase requests.
Background of the Development
Discussions regarding credit card limits have remained on the agenda since the beginning of 2026. The comprehensive economic plan announced in August aimed to re-establish the balance between salary increases and credit policies. The discussions that started in September over the 400,000 TL detail in credit card limits were essentially an effort to make the system more transparent and sustainable.
Historically, credit card limits in Turkey were determined at the discretion of banks and based on customers' past payment performance for a long time. However, with the decisions implemented in the last quarter of 2026, the BRSA tied this process to a more centralized and controllable mechanism. In particular, changes in minimum payment rates aim to protect consumers entering a debt spiral and strengthen banks' risk management.
The fundamental motivation behind these regulations is to protect the local financial system against fluctuations in the global economy. As emphasized in local sources such as Bursa Saati Gazetesi in October, warnings about paying attention to minimum payment rates have become part of a public information strategy aimed at increasing consumers' financial literacy.
Expert and Industry Insights
Economists and banking sector representatives state that although these regulations create a 'liquidity tightening' in the short term, they are of critical importance for financial stability in the long term. Experts' views are gathered under the following headings:
- Linking limits to income is the most effective mechanism to prevent over-indebtedness.
- Updates to minimum payment rates will help banks reduce their non-performing loan (NPL) ratios.
- Consumers will now need to provide more realistic income documents for limit increase requests, which may contribute to a reduction in the informal economy.
Banking analysts state that clarifying the boundaries between phone loans and credit card limits is aimed at breaking the consumer habit of 'closing debt with debt.' This is a strategic step taken to ease the burden on the financial system.
Industry representatives predict that banks will now follow a more selective credit policy and that this will initiate a 'quality-focused' era in credit card usage. Customer loyalty and payment performance are becoming more decisive factors in limit determination than credit scores.
Economic and Social Implications
The social implications of these regulations will be quite significant, especially for middle and low-income consumers. Reducing or limiting credit card limits may cause a slowdown in spending habits. Although this carries the risk of creating a short-term stagnation in the retail sector, it is seen as part of demand management within the scope of the fight against inflation.
From an economic perspective, keeping household debt under control will strengthen the capital adequacy ratios of the banking sector. These steps taken by the BRSA increase the financial system's resistance to external shocks while also ensuring that individuals achieve a more conscious borrowing structure.
On the other hand, new regulations made via e-Government and digitized financial processes allow consumers to track their own limits and debt status more transparently. This transparency stands out as an element that reinforces the trust relationship between the bank and the customer.
Future Projections and Outlook
In the coming period, we are entering an era where credit card limits will be managed entirely by an income-based algorithm. The calendar planned by the BRSA for the end of 2026 and early 2027 points to stricter audits and a more transparent credit scoring system. It is vital for consumers to keep their income declarations up to date for limit increase requests and not to miss their minimum payments to protect their financial health.
Possible risk scenarios include the temporary contraction that limit restrictions may create in consumption-oriented sectors. However, the opportunity scenario is that the Turkish economy will be built on more solid foundations with a healthier borrowing structure and a consumer base with high financial literacy. The year 2026 will be recorded as the beginning of the year of 'discipline' in credit card usage.
💬 Yorumlar 0
Henüz yorum yapılmamış. İlk yorumu siz yazın!